Weekend Market Report-10/17/26- A Brutal Week
The week of October 12–16 was a brutal one for the growth/AI complex.
The Scorecard
S&P 500: −1.95% to 7,659.44 (worst week since June)
Nasdaq Composite: −4.48% to 26,140.03 (also worst since June)
Nasdaq-100: −5.49%
Dow: +0.67% to 52,002.41
Russell 2000: −3.05%
Tech (XLK): −7.7%
Semis (SOX/SMH): roughly −11% (biggest weekly drop since April 2025)
VIX: jumped from the mid-teens to ~20
10-year yield: eased from ~5.24% to ~5.10%
WTI crude: surged through $100 (closing the week near $101); Brent around $110
The market split cleanly. Money rotated into staples, healthcare, energy, and banks (which delivered solid Q3 prints earlier in the week). The AI infrastructure and chip complex got crushed.
What Drove the Damage
Two overlapping forces:
1-AI debt and capital-constraint fears. Investors suddenly cared about how the data-center buildout gets financed at higher rates. CoreWeave (CRWV) bond yields spiked toward 15%, CDS spreads blew out, and the contagion hit other neoclouds hard. CRWV finished the week down roughly 25%; Nebius (NBIS) took a ~15%+ hit and briefly fell below $200. Broadcom’s Hock Tan comments about capital potentially limiting AI spending didn’t help. The selloff spread to the broader chip complex (MU, AMD, AVGO, NVDA, INTC all down sharply) and higher-multiple software/AI names. Palantir (PLTR) dropped more than 7% on Friday alone and finished the week down double digits despite some positive analyst notes.
2-Hot inflation + oil/Hormuz. September CPI printed 3.7% year-over-year (a touch above expectations); PPI was also firm. At the same time, Iranian attacks on shipping around the Strait of Hormuz intensified, diesel tightness persisted, and WTI punched through $100. Energy was one of the better sectors; everything rate-sensitive or long-duration got hit. Chair Warsh’s remarks at the IMF didn’t give the market a clear dovish out.
Friday’s close left the S&P and Nasdaq below their 50-day moving averages after a failed attempt at new highs earlier in the month. Classic “breakout that didn’t stick” tape, especially in the former leaders.
Week Ahead (Oct 19–23)
Earnings take the spotlight. The calendar is heavy with names that matter for sentiment:
Tuesday: Netflix (NFLX) after the close; also GE Aerospace, GM, RTX, Halliburton, and others.
Wednesday: Tesla (TSLA) and Meta (META) after the close — the two big ones. IBM and Texas Instruments also report.
Thursday: Procter & Gamble, Lockheed Martin, Comcast, Western Digital, among others.
Friday: American Express.
Investors will be listening for any color on AI spending sustainability, advertising demand (Meta), vehicle margins and robotaxi progress (Tesla), and free-cash-flow trajectory (Netflix). A clean beat-and-raise from Meta or constructive commentary from Tesla on margins/FCF could stabilize the complex; weak guidance or more talk of higher capex without clear returns would extend the pain.
Macro is lighter: housing starts/permits mid-week, weekly jobless claims Thursday, University of Michigan sentiment Friday. The Fed is in blackout ahead of the October 27–28 meeting, so no new official commentary. Oil and Hormuz remain the wild cards—any further escalation or disruption in flows keeps energy bid and pressure on rate-sensitive/AI names. Yields backing up again would be unwelcome.
Last week reminded us that the AI trade isn’t immune to financing reality or higher-for-longer rates. The Dow holding up while the Nasdaq got smoked shows rotation is real, not just noise. The coming week hinges on whether big earnings prints can put a floor under the leaders or whether debt/capex skepticism has further to run. Volatility is elevated, and the technicals are damaged — trade accordingly and size positions for continued chop until the tape proves otherwise.
A bear market is defined as a 20% pullback. The indexes are nowhere near that, but we have seen major damage under the hood, with some high flyers down 30 to 40%.
Bond yields eased last week, but not for the constructive organic reasons we want. Yields dipped because of fear and a flight to bonds as a safety net; as a result, rates dipped. WTI rose about $10 last week after dipping. Unless and until it dives, rates won’t cooperate to fall, and the market will stay on the defensive.
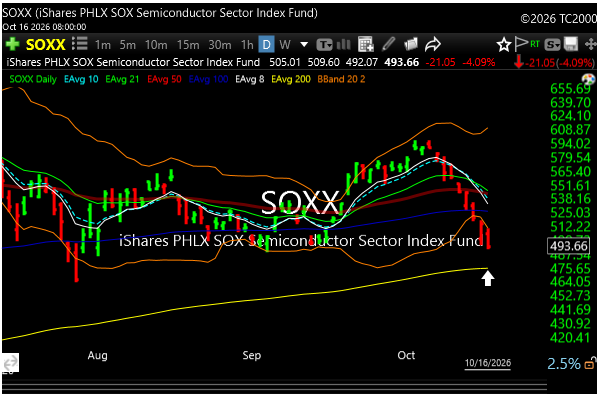
The chip sector is in waterfall mode and has led the market. Now down 9 days in a row. Support is thin at 490, and the 200EMA is down at 474.63. That might be the magnet for SOXX before we see any recovery.
Earnings start hot and heavy next week. Good luck, and I will see you bright and early in the Discord room.
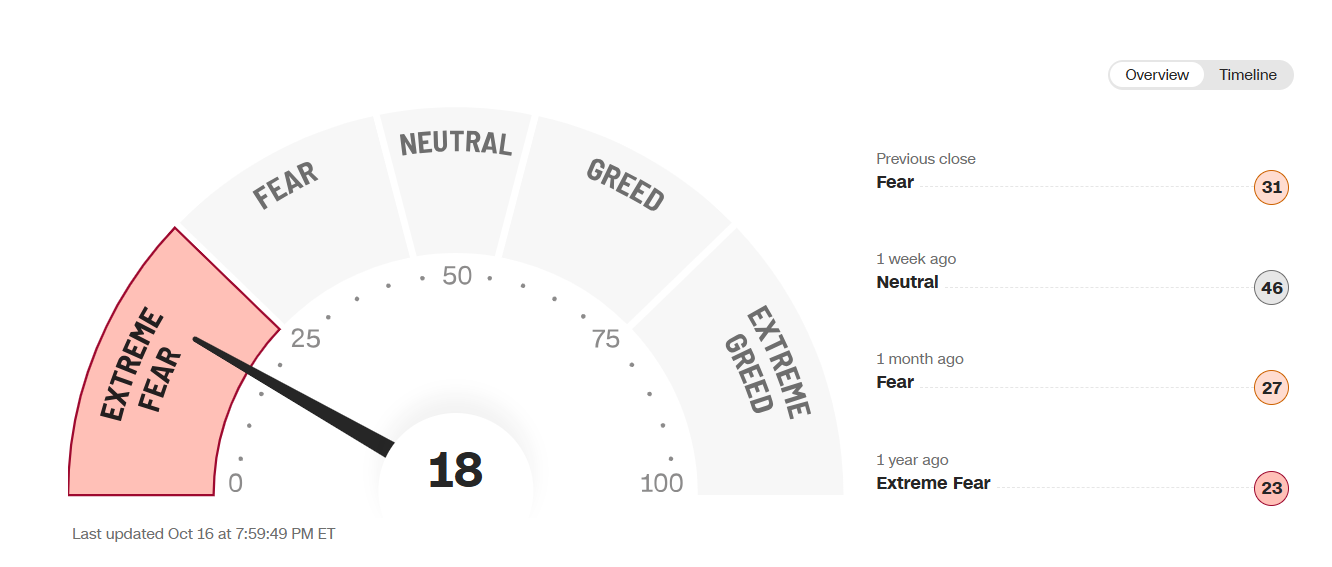
I like “Extreme Fear” readings, as you can see above. More times than not means a bottom is in or very close.